

Hyundai Corporation Holdings (KOSPI: 227840, 현대코퍼레이션홀딩스) collects a fee every time somebody sells a generator, a power tool or an air conditioner under the HYUNDAI logo somewhere outside Korea. It also owns a quarter of a ₩8.7 trillion trading house, imports frozen meat, makes cardboard boxes in Cambodia and grows shiitake mushrooms in Lancashire. The whole thing is worth ₩122.2bn (US$86m) and no broker has published a report on it since May 2021.
Two companies here share almost the same name, so let me fix the labels first.
Holdco is Hyundai Corporation Holdings (227840). That is the one I am writing about.
Tradeco is Hyundai Corporation (KOSPI: 011760, 현대코퍼레이션), the general trading house. Holdco owns 26.38% of it.
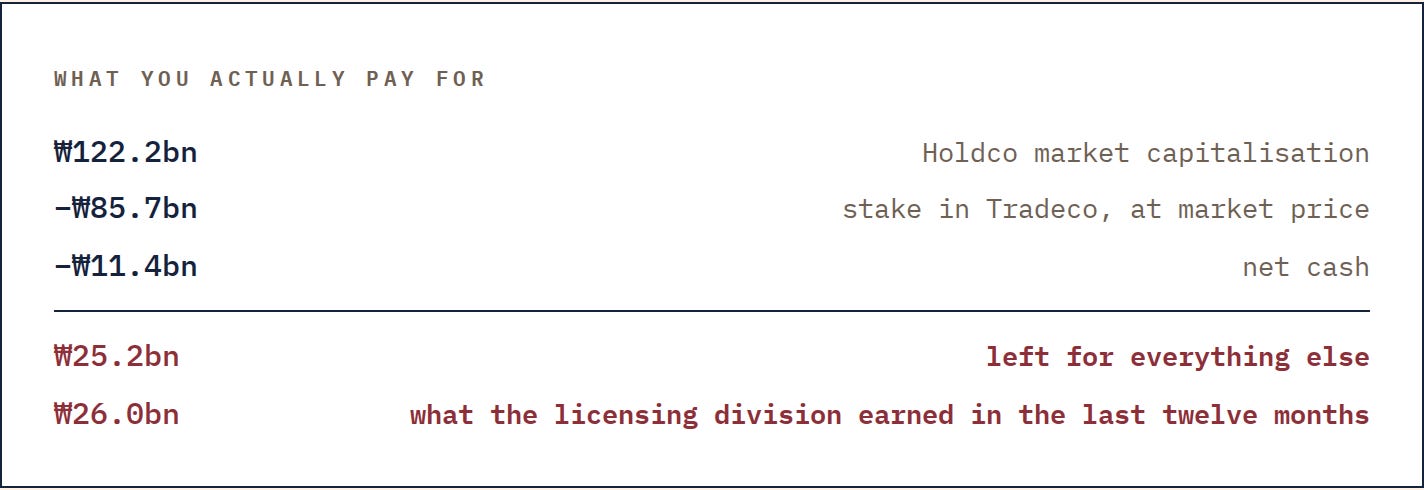
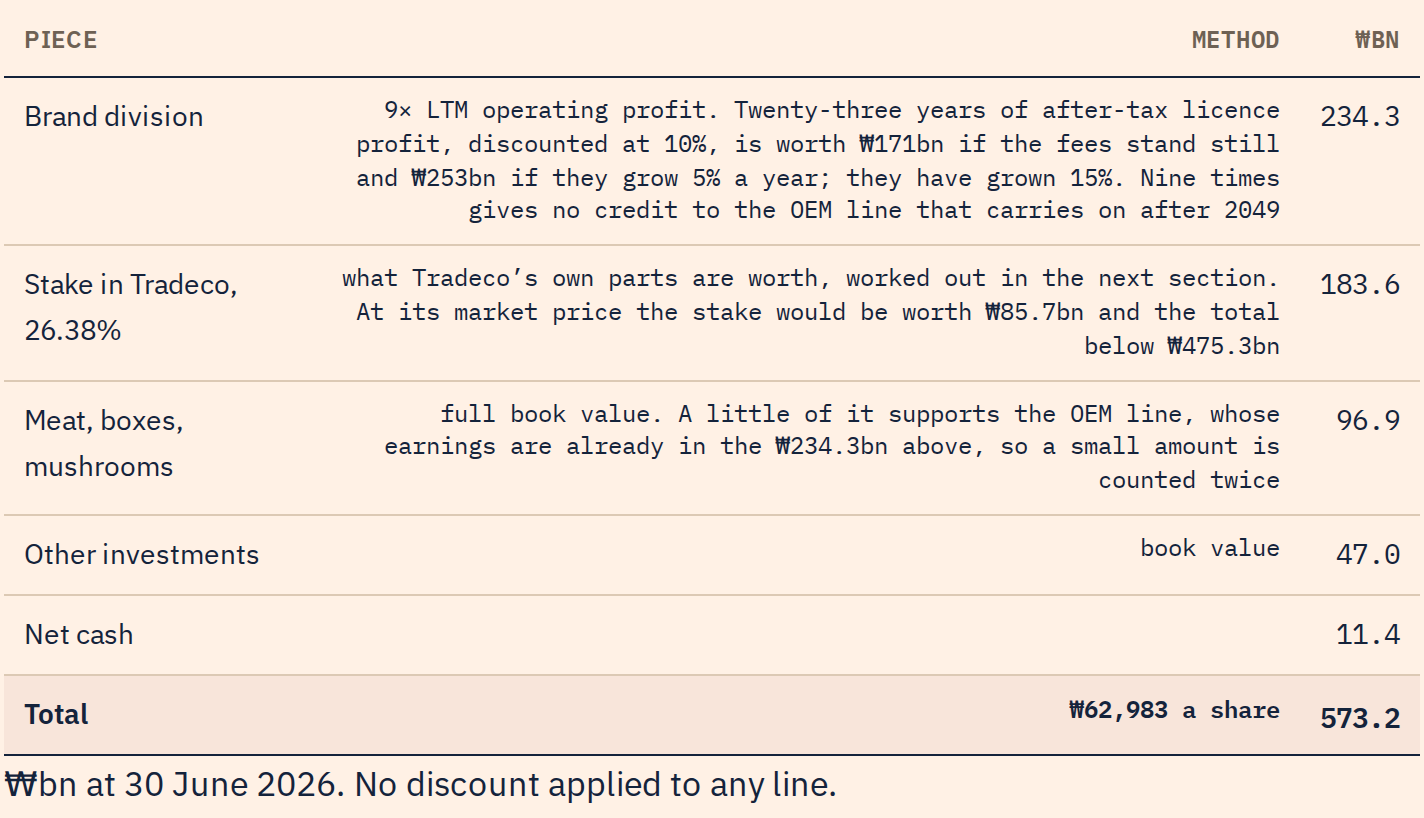
Slightly less than one year of the brand division’s operating profit, for the brand division. And the frozen meat, the mushroom farms, the packaging plants, the property fund and ₩47bn of other investments arrive attached to it, as a gift.
I like the asset for two reasons.
It lasts, and it grows. The licence runs to 2049 and the rent on it was paid in full in 2019. The fees have grown 12% a year since 2020 and the profit on them 15%, and the money comes from independent dealers and manufacturers across the Americas, Europe and Asia, none of whom has anything else to put on the box.
It needs almost no capital. ₩37.8bn of licence fees came in over the last 12 months and ₩26.0bn survived as operating profit, sixty-nine won in every hundred. The licence itself uses none of the ₩96.9bn the group has tied up in inventory, farms and factories, so that profit arrives as cash.
Neither of those is in the price. Value every part fairly and I get ₩62,983 a share. The stock is ₩13,430.
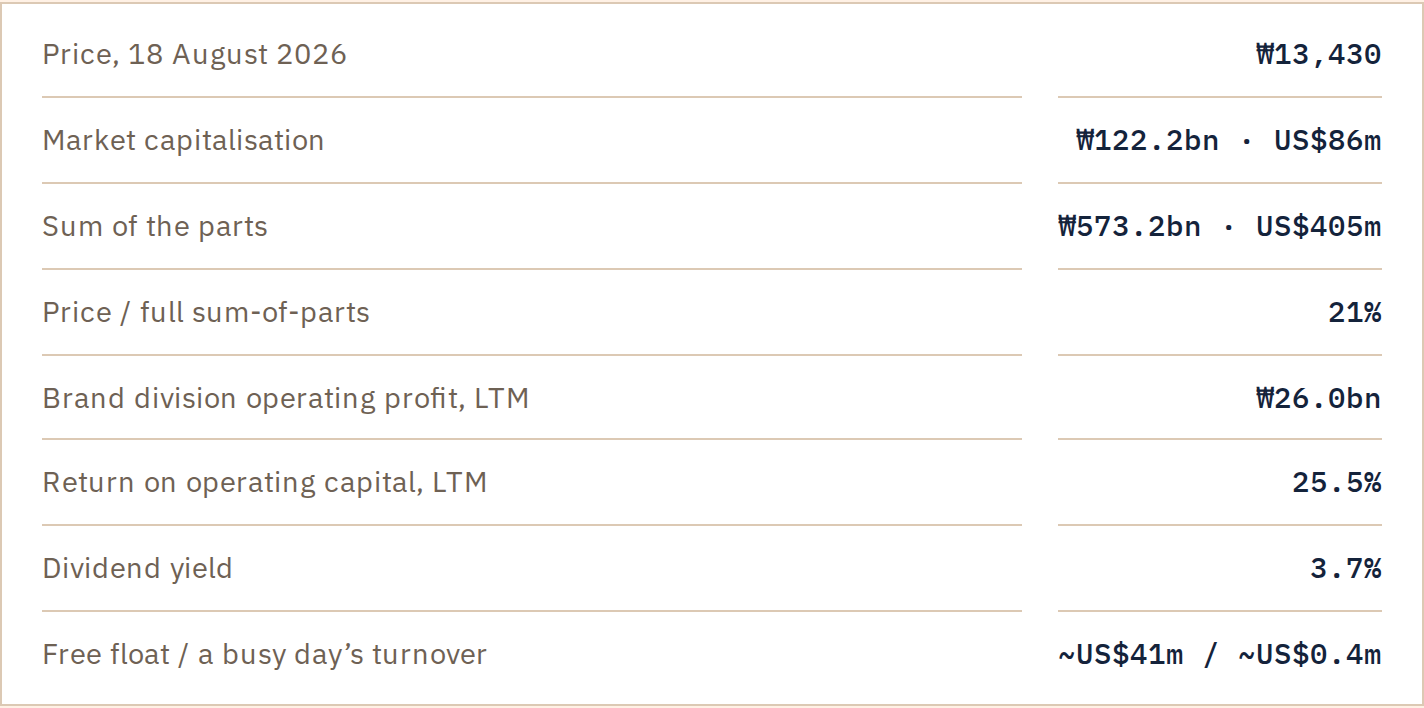
All figures are LTM, meaning the year to June 2026: full-year 2025, less the first half of 2025, plus the first half of 2026. Everything comes from filings on DART.
Holdco owns a quarter of Tradeco, so it must count a quarter of Tradeco’s profit as its own, even though the cash mostly stays at Tradeco. And when it bought more Tradeco shares in the second quarter at roughly half their book value, the rules made it count that gain as profit straight away. No money arrived either time, which is why reported profit is no use here. Everything below uses operating profit.
What the licence actually earns
The brand division and the licence are not the same thing.
Royalty revenue is a fee. A foreign manufacturer sells its own generator or power tool under the HYUNDAI mark and pays Holdco a slice. Holdco buys nothing and ships nothing.
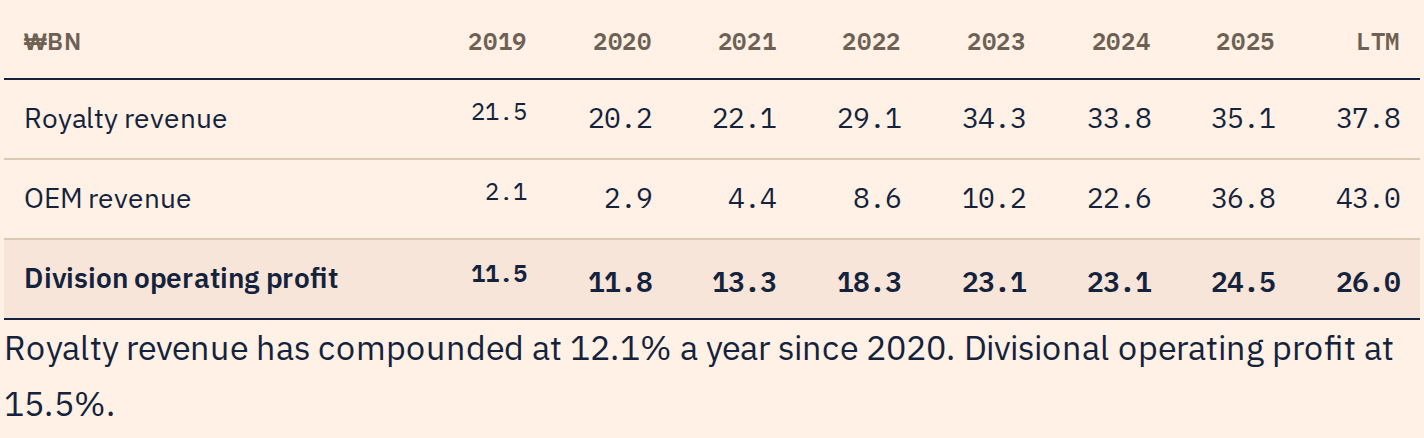
OEM merchandise is an ordinary trading business sitting in the same division. Holdco has generators and air conditioners built for it, buys them and sells them on. That line went from ₩2.1bn to ₩43.0bn in seven years, and it is the only reason the division’s margin looks like it is collapsing. The ₩26.0bn of divisional operating profit includes whatever the OEM line contributes, and the filings do not split the two.
Royalty revenue compounds. OEM merchandise adds revenue and almost no profit.
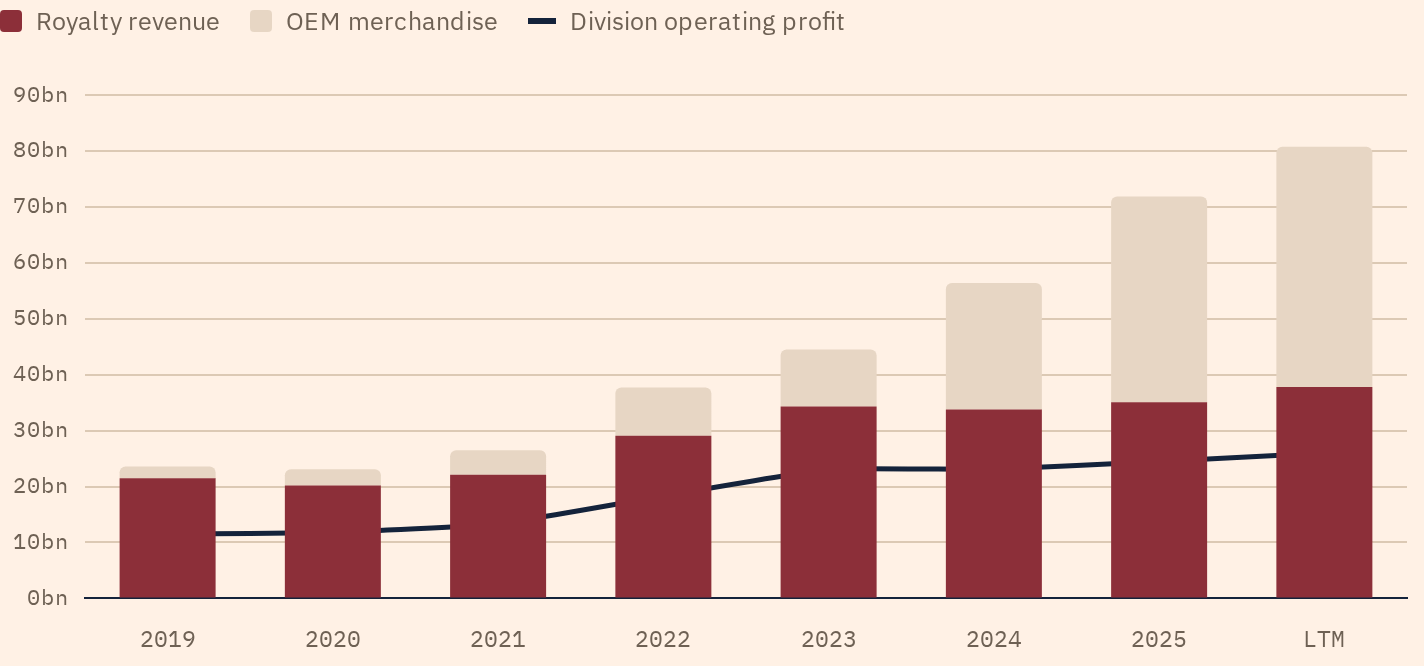
₩bn. Divisional operating profit tracks the royalty line, not the revenue line.
How long it runs
About ₩6bn of the ₩37.8bn comes from companies inside the group, at rates written into the filings. The rest comes from outsiders, mostly in the Americas and Europe.
In 2019 the wider Hyundai family sorted out who legally owns the name. Holdco handed the mark to HD Hyundai, the shipbuilder, and took back a thirty-year licence in the same deal, paying all thirty years up front. So it collects royalties and pays no rent, and the licence ends on 31 January 2049. On the balance sheet the mark and the liability against it cancel out, which is why a business earning ₩26bn a year is carried at ₩0.1bn.
After that Holdco may use the mark directly, with no time limit. Direct use means putting the badge on your own products, not renting it out for a fee, so the fee stream has an end date and no renewal terms yet. But direct use is exactly what the OEM line already does, and that line has grown from ₩2.1bn to ₩43.0bn of revenue in seven years. What ends in 2049 is the fee, not the right to use the name.
What else Hyundai Corporation Holdings owns
Frozen meat. The worst business here and the biggest: ₩129bn of revenue in 2025 at a 0.4% operating margin, with market share in imported pork and chicken falling for three years. In the six months to June the inventory went from ₩32.9bn to ₩51.3bn and group operating cash flow turned negative, so every won the licence earned went into a freezer. Book value: ₩51.3bn.
Mushrooms. The one part with a moat. The company says Bulla Mushrooms is the only producer in Australia certified for organic button mushrooms, and that Smithy Mushrooms in Lancashire is one of two British growers that make their own substrate. Between them they supply Coles, Woolworths, Tesco, M&S and Booths, and the operating loss narrowed from ₩616m to ₩53m in the last half year. The farms and the packaging plants share ₩46.1bn of property and equipment between them, and the filings do not say how it splits.
Cardboard boxes. Two plants in Cambodia and one in Indonesia, selling to local brewers and to global shoe and clothing brands. ₩0.9bn of operating profit on ₩20.8bn of revenue in 2025, and the other half of that ₩46.1bn of plant.
The investments. A Seoul property fund, a Capstone trust, a venture vehicle, a stake in a packaging maker and a quarantine joint venture in Cambodia, ₩47bn at book. They paid Holdco about ₩0.8bn of dividends in the first half.
Return on capital at Hyundai Corporation Holdings
Leave out the investments, the cash and the tax assets, and Holdco has ₩96.9bn tied up in its businesses: ₩51.3bn of frozen meat, ₩18.0bn of receivables, ₩46.1bn of farms and packaging plants, ₩1.4bn of goodwill, less ₩32.8bn of payables.
Almost none of it belongs to the licence.
The brand division has out-earned the entire group in all eight periods
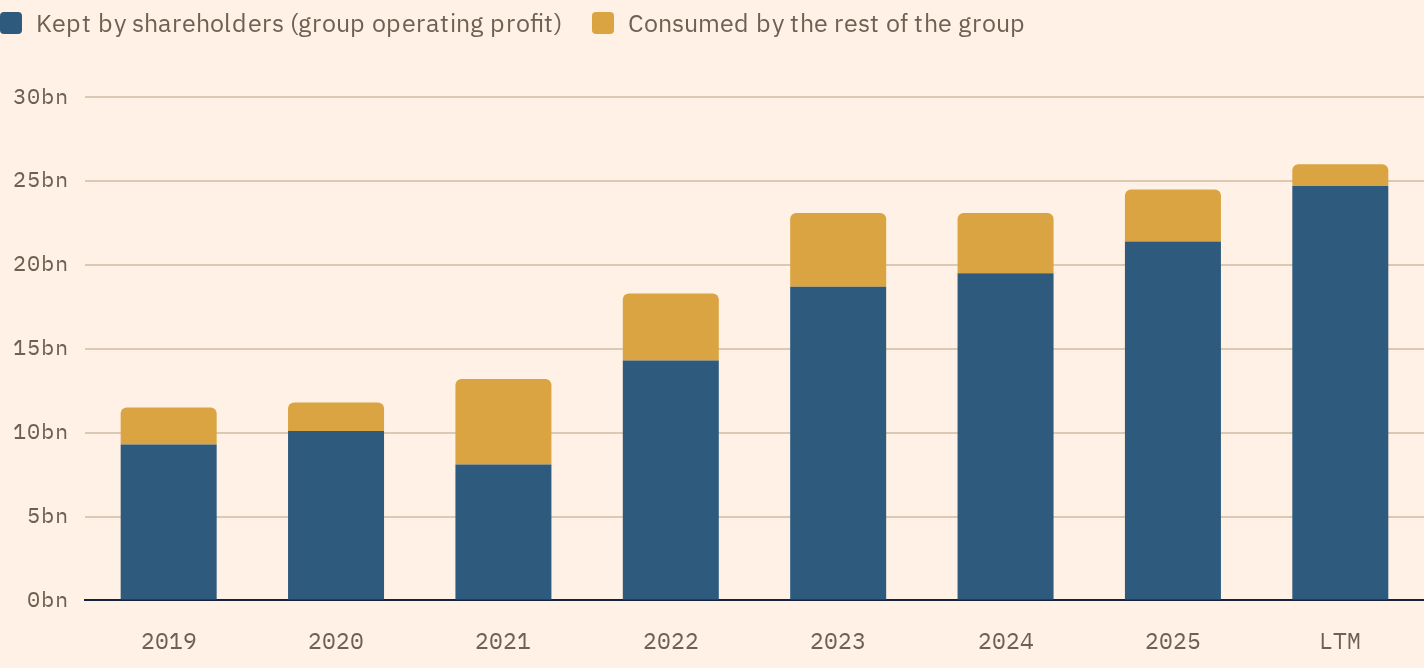
₩bn. Each bar is the brand division’s operating profit. The gold portion is what the other businesses took out of it: ₩25.5bn over eight periods, a fifth of what the whole company is worth today.
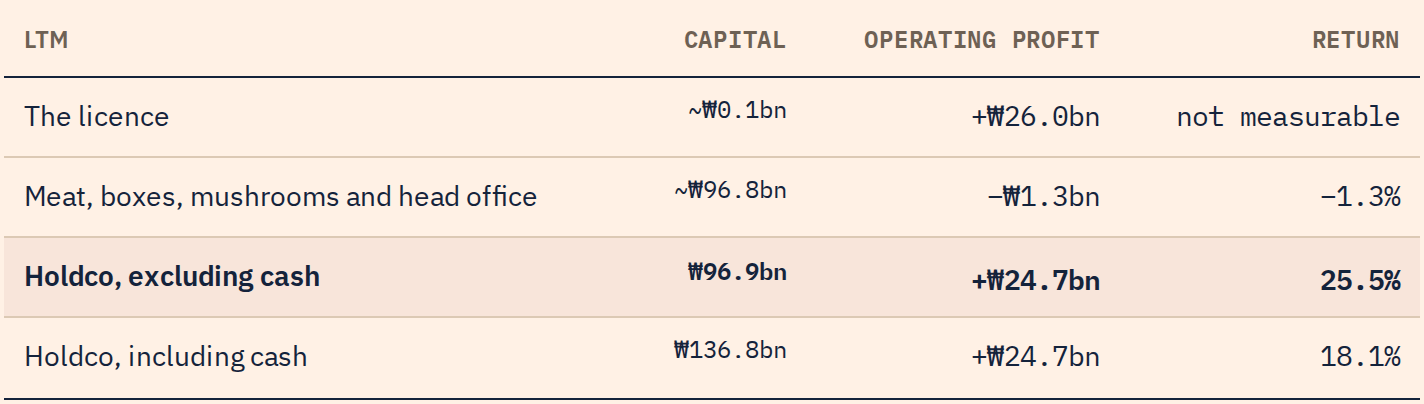
Return on capital is operating profit divided by operating capital: operating assets less trade payables and other non-interest-bearing operating liabilities. Investments are excluded because their income is reported bellow the operating line and I value them separately.
Sum of the parts: Hyundai Corporation Holdings
What the parts are worth against what the market pays
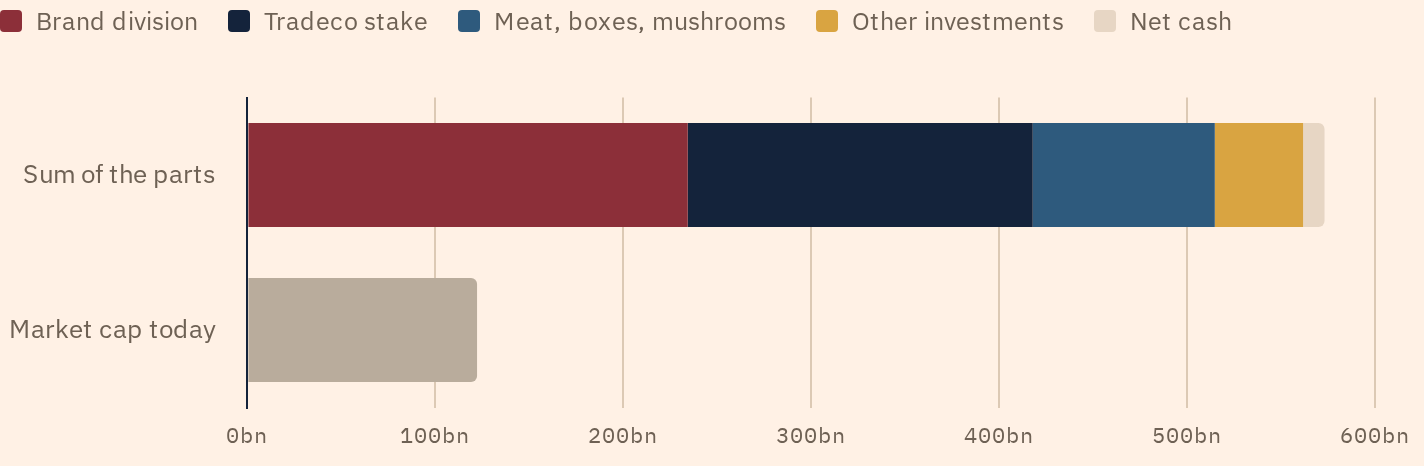
₩bn. No discount applied to any component.
The other half: Hyundai Corporation
Five years ago Tradeco was a steel broker. Steel made 42% of operating profit and auto parts 6%. Today auto parts are the largest division, steel is shrinking, and operating profit has compounded at 29.4% a year since 2020.
Operating profit by division, and what replaced steel
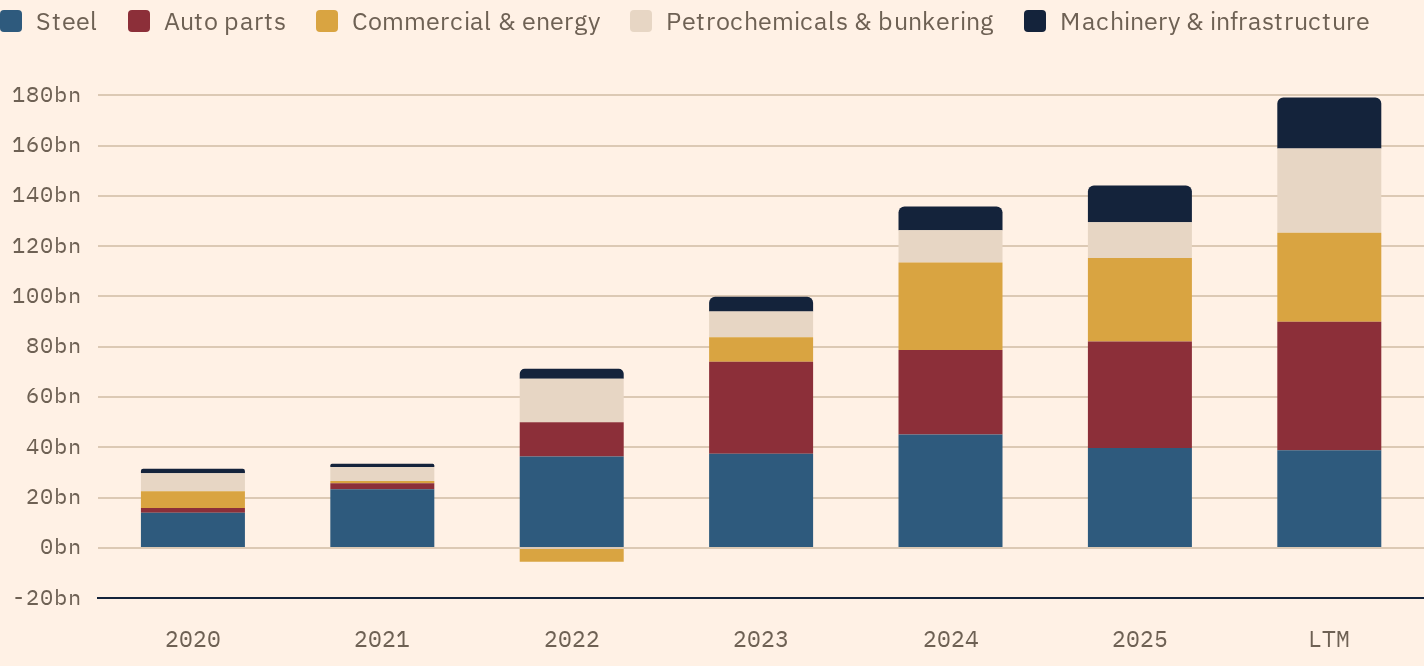
₩bn. A small “other” division is excluded, so the bars do not foot exactly to the totals. Profit from the Oman and Yemen LNG stakes never reaches operating profit at all: it was ₩31.6bn in 2023 and ₩34.9bn in 2022, reported below the line.
Revenue tripled and the margin on it nearly doubled
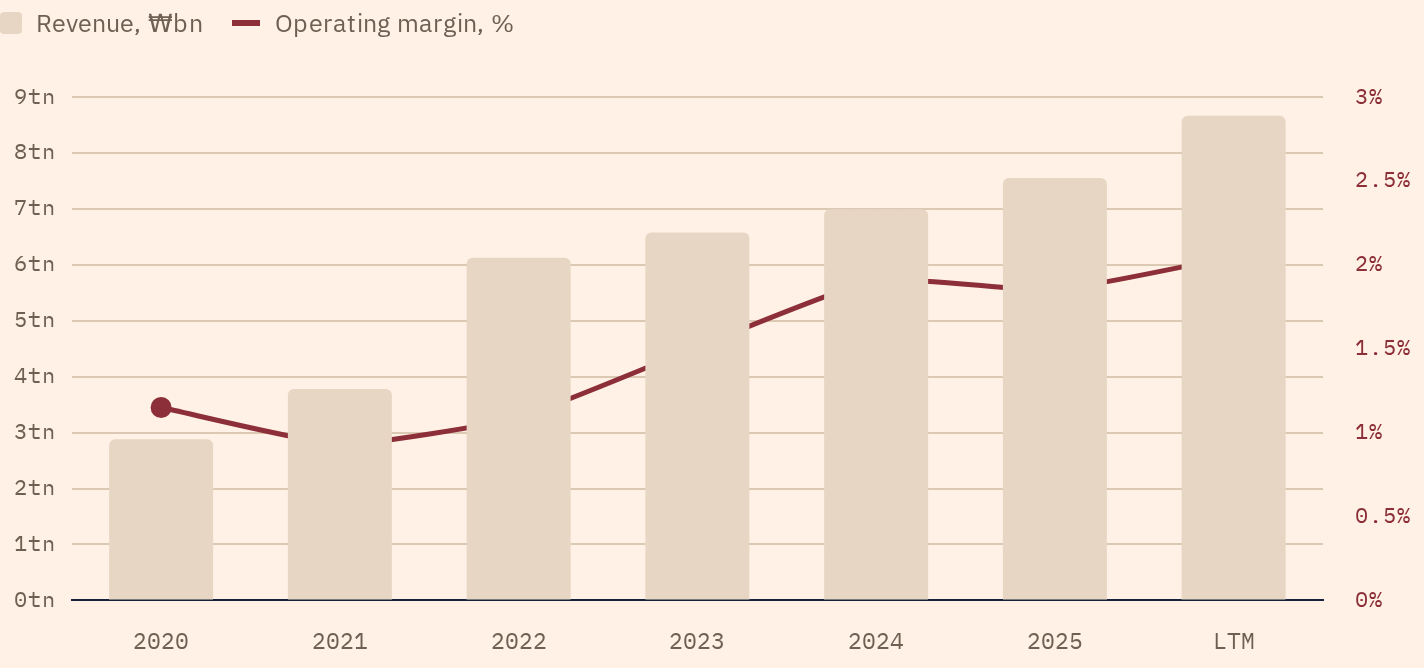
Two per cent still sounds thin, and it is. But it is twice what this business made in 2021 on three times the revenue. Tradeco spent the difference consolidating auto parts makers in Korea, China and India and a forklift distributor in Australia.
Return on operating capital is 13.3% excluding cash and 10.4% including it, about half what Holdco earns.
Tradeco earns profits but not cash. Operating cash flow was minus ₩69.9bn in 2023, plus ₩40.5bn in 2024, minus ₩294.7bn in 2025 and minus ₩142.9bn in the first half of 2026. The more it buys and sells, the more money sits with customers who have not paid yet, and that money is borrowed. Net debt is ₩847bn against ₩767bn of equity. The market is not wrong to discount that.
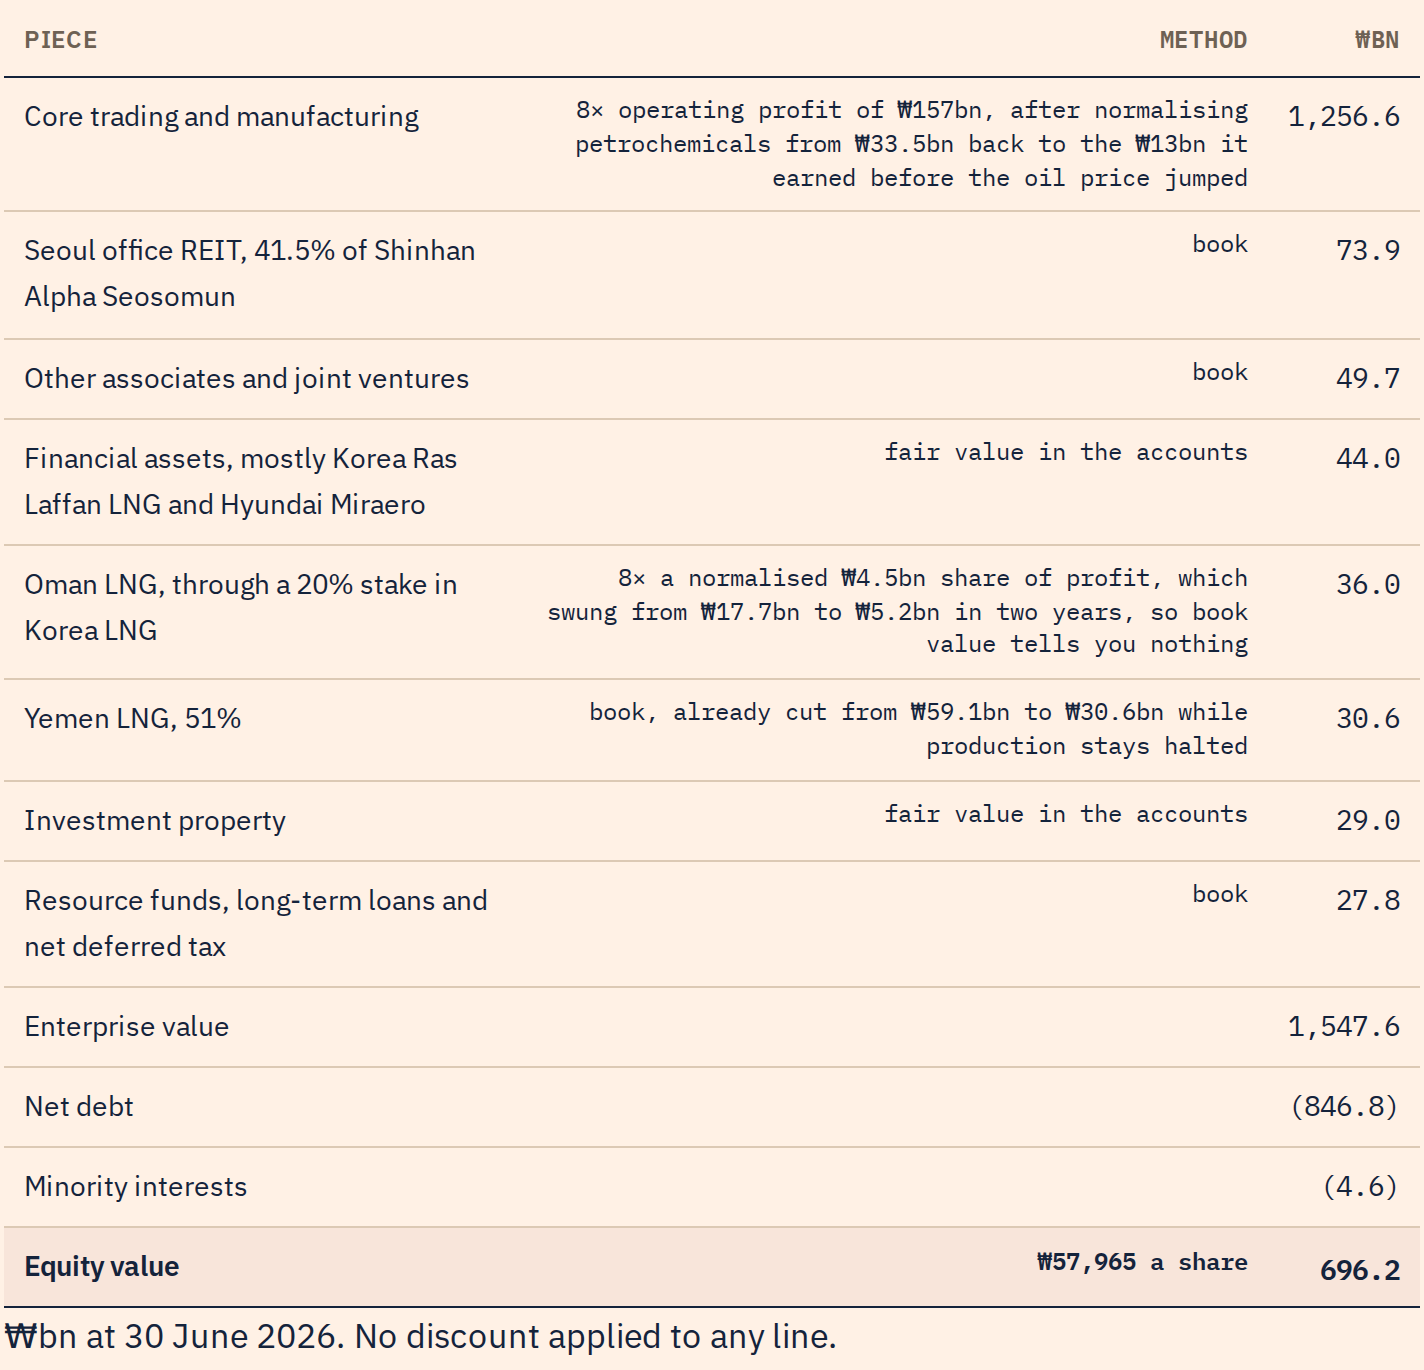
The stock is ₩27,050, so 47% of that. And that is the double discount: Holdco owns a quarter of Tradeco and then trades at a discount to that itself.
What management does with it
The dividend yield is 3.7%. Holdco pays out ₩4.4bn a year and earns ₩24.7bn at the operating line, so most of it stays inside. Holdco raised its dividend twice in its first three years as a listed company, from ₩200 to ₩400 to ₩500, and has not touched it since 2017. Operating profit has more than tripled since 2018. Tradeco moved once in the same nine years, from ₩600 to ₩700 in 2024.
Dividend per share, 2017 to 2025
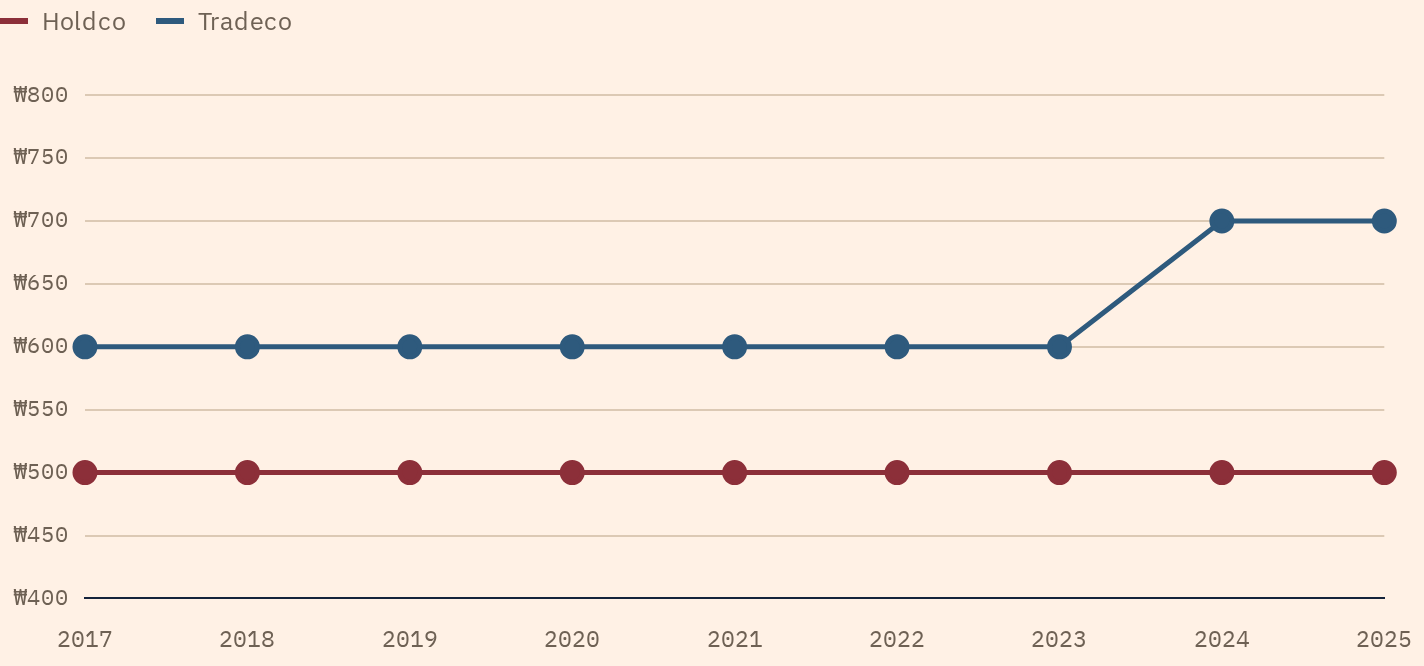
₩ per share. Both companies have paid a dividend every year since listing, and both keep it small: Holdco is legally allowed to distribute ₩89.1bn.
Korea’s three new corporate laws, and what they mean here
Neither Holdco nor Tradeco has ever published a value-up plan, Korea’s 2024 disclosure in which a company says what it thinks it is worth and how it intends to close the gap. That is the case for the discount, and Korea has spent the past year legislating against it.
Treasury shares must now be cancelled. Holdco holds 3.07% of itself and Tradeco 9.21%. A law effective 6 March 2026 gives both until roughly September 2027 to cancel them or ask shareholders for permission to keep them. Either way, both boards have to raise the subject of returning capital for the first time.
The controlling family’s vote is capped at 3%. When shareholders elect the audit committee, the family and its allies now share a single 3% vote between them instead of 3% each. Only 28.8% of eligible shares voted on that item in 2026, and 47.6% of the company sits outside the control bloc. March 2027 is the first meeting under the new rule.
Small shareholders can now concentrate their votes. Companies with more than ₩2 trillion of assets can no longer opt out of cumulative voting, which lets a minority put every vote behind one board candidate instead of spreading them across all the seats. Holdco is too small to be caught. Tradeco is not.
All three have passed. What I do not know is whether these boards do the minimum or take the hint.
What could break it
Working capital. The frozen meat inventory is the live one. It absorbed every won of first-half operating profit and more. Watch the third quarter.
Capital allocation. The licence generates cash and the board keeps finding somewhere to put it that is not the shareholders. Nothing stops the next ₩50bn going into another business like the meat one.
The control bloc. 49.34% held together by an eleven-year-old voting agreement. Nothing happens if they do not want it to.
Tradeco’s balance sheet. ₩847bn of net debt funding a receivables book that grew 56% in six months. If one large counterparty fails, a 2% margin does not absorb it.
What would make me wrong. Royalty revenue stalling for two years, a write-down on the meat inventory, or the March 2027 meeting passing with nothing changed and the discount still where it is in 2028.
What it comes down to
The best business in this company earned ₩26.0bn in the last 12 months and sits on the balance sheet at ₩0.1bn.
The stock is at 21% of what the parts are worth. It does not have to reach 100% for this to work. It only has to stop being 21%.
Sources. Hyundai Corporation Holdings (현대코퍼레이션홀딩스, KOSPI: 227840) and Hyundai Corporation (현대코퍼레이션, KOSPI: 011760) filings on DART: annual reports for 2020 through 2025, the half-year reports to June 2026, the corporate governance report of 1 June 2026, the shareholders’ meeting documents of February and March 2026 and the large-holding disclosures. Korean Commercial Act amendments of July 2025, August 2025 and February 2026. Market data as of 18 August 2026, at ₩1,416.47 to the dollar.
How I work. I read the Korean filings myself. AI helps me with translation and with checking the arithmetic. Every judgement, model and conclusion here is mine.
Disclosure. Assume I own shares in every company I write about, and read accordingly. I don’t disclose individual positions or sizes.
Disclaimer. This is analysis for discussion, not investment advice, and not a recommendation to buy or sell anything. I’m not your adviser. The figures come from primary filings but I make mistakes, so check them yourself before you act. Micro caps carry real liquidity and volatility risk, and you can lose your money.
Fair. I don't think the discount closes without capital allocation changing, and I said as much in the piece.
Two things stop me calling it a trap, though. The core is growing rather than melting: royalty revenue has compounded at 12% a year since 2020 and divisional operating profit at 15%. A value trap is usually something cheap that is quietly shrinking, and this isn't.
And a couple of Korean investors pointed out something I had missed. The company charges its affiliate 2% of gross profit for the brand, which works out at roughly 0.07% of that affiliate's revenue. SK and LG charge 0.2%, CJ 0.4%. Normalising just that one rate would put several billion won a year into a division that made ₩26bn.
Doesn't make the capital allocation good. Just means there's more than one way it improves.
Smells of value trap with that capital allocation